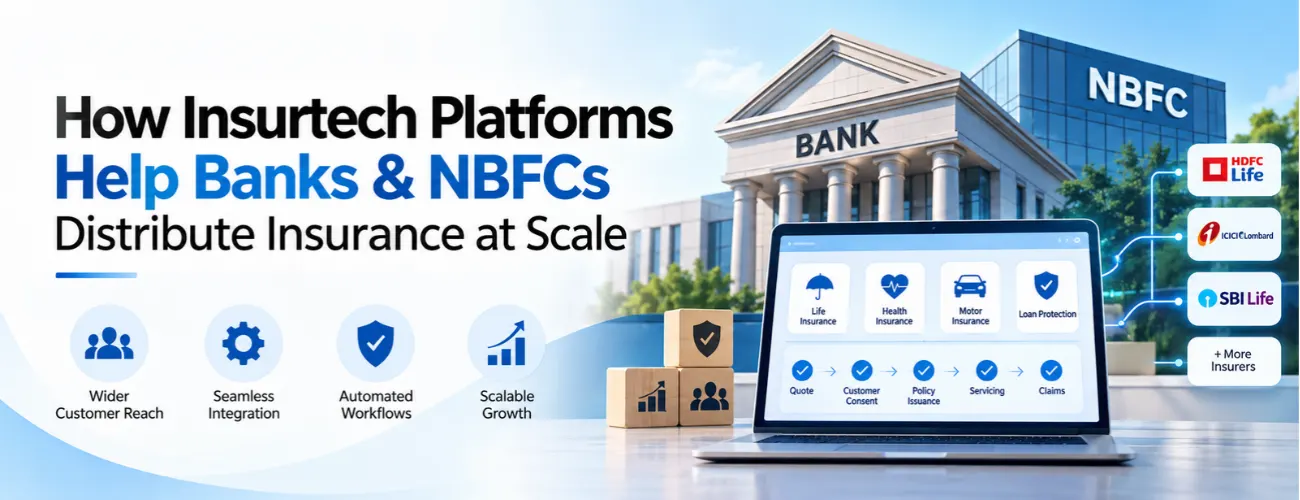
- Bancassurance Software: A connected digital workflow that empowers banks and NBFCs to manage quotations, policy sales, instant issuance, claims servicing, and insurer reporting from a single interface.
- API-Based Insurance Distribution: Offers eligible insurance products contextually embedded within digital banking and loan disbursement journeys.
- Automated Back-Office Operations: Multi-party commission reconciliation, customer consent trails, and IRDAI compliance logs underpin frictionless scaling without operational overheads.
- FondosTech Solutions: Pre-built specialized modules like FT Lending Insure and FT Embedded Insure integrate insurance natively into existing financial workflows.
Introduction: The Growing Role of Banks & NBFCs in Insurance
Banks and Non-Banking Financial Companies (NBFCs) have an extensive existing customer base, robust digital lending infrastructure, and frequent customer touchpoints. In India's evolving financial ecosystem, this has made them primary and vital channels for insurance distribution.
However, selling insurance to hundreds of thousands of borrowers and account holders is far more intricate than simply presenting financial products. Financial institutions must coordinate complex insurer integrations, verify customer consent, manage real-time policy issuance, service post-sale queries, fulfill regulatory obligations, and reconcile multi-party commissions.
This is where the transformative role of bancassurance software and dedicated insurtech platforms for banks becomes indispensable. Modern insurtech platforms bring multiple insurance workflows into a unified, connected operating system—enabling banks and NBFCs to dramatically scale insurance distribution without a corresponding surge in manual labor, administrative overhead, or operational friction.
"Insurtech platforms bridge fragmented insurance workflows into a unified operating backbone, allowing banks and NBFCs to scale policy volumes by 5x–10x without proportional overhead growth."
What is an Insurtech Platform for Banks?
Bancassurance software (or an insurtech platform for banks) is a purpose-built digital infrastructure that enables commercial banks, NBFCs, housing finance companies (HFCs), and authorized financial distributors to offer, issue, and service insurance products seamlessly across their existing customer journeys.
It serves as an intelligent bridge connecting financial institutions with multiple insurance carriers while orchestrating mission-critical activities:
Retrieves real-time premiums and customized policy terms across multiple partner insurers through unified APIs.
Auto-fills borrower details from core banking/LOS data and logs immutable, audit-ready customer consent records.
Dispatches payment confirmations, binds coverage instantly, and generates digital policy dockets within seconds.
Manages renewals, endorsements, loan foreclosure refunds, and digital claims routing without disconnected spreadsheets.
For example, when a borrower applies for a personal loan, the bank's digital lending system can present an eligible credit life insurance plan directly within the loan approval flow. Instead of managing a separate manual application, the integrated insurtech system displays the offer, captures customer consent, submits proposal data to the carrier, and confirms policy issuance simultaneously.
While bancassurance traditionally applied to commercial banks, modern insurtech platforms extend these capabilities to NBFCs, housing finance companies, microfinance institutions, and digital lending fintechs operating under authorized corporate agency or distribution arrangements.
7 Ways Insurtech Platforms Assist Banks & NBFCs to Distribute at Scale
Scaling insurance distribution requires institutional-grade software that eliminates manual handoffs while upholding compliance. Here are seven core capabilities modern insurtech platforms provide:
The single greatest operational bottleneck in multi-partner bancassurance is managing diverse insurer systems. Each insurer maintains unique product specifications, data schemas, underwriting rules, and issuance protocols.
An API-based insurance distribution platform functions as a standardized integration layer between the financial institution's Core Banking System (CBS) or Loan Origination System (LOS) and supported insurance carriers.
- Dynamic Product & Quote Retrieval: Fetches up-to-date insurance products and premium calculations via normalized API endpoints.
- Unified Proposal Submission: Maps customer and collateral data once, routing proposals according to carrier-specific specifications.
- Instant Policy Reconfirmation: Receives policy numbers, digital COIs (Certificate of Insurance), and payment confirmations in real time.
- Connected Servicing Pipelines: Synchronizes policy endorsements, cancellation requests, and reporting across all carrier interfaces.
Loan origination and disbursal represent natural, high-intent touchpoints to provide critical financial protection:
- Vehicle & Auto Loans: Embedded motor insurance and asset protection cover.
- Personal & Business Loans: Credit life insurance, personal accident, and critical illness coverage.
- Home & Mortgage Loans: Property insurance and loan-linked term protection.
Historically, attaching insurance required paper forms, separate cheque collections, and manual uploads. An embedded insurance platform synchronizes the entire lifecycle through a structured 6-step workflow:
6-Step Integrated Lending & Insurance Workflow
FondosTech FT Lending Insure: Purpose-built for banks and NBFCs to automate loan-linked insurance, track policy lifecycles, eliminate orphaned records, and handle foreclosure refunds with zero manual reconciliations. Learn more about FT Lending Insure.
Beyond credit journeys, financial institutions interact with millions of customers daily via mobile banking apps, UPI payment portals, net banking portals, and investment desks.
Embedded insurance offers contextual protection at the precise point of transaction—such as travel insurance when booking tickets, cyber fraud protection on card activations, or health micro-insurance with recurring deposits.
By integrating lightweight SDKs and REST APIs, banks can offer instant, bite-sized protection without redirecting users to disjointed third-party portals, driving up to 2x higher conversion rates.
FondosTech FT Embedded Insure: Provides plug-and-play API integrations for mobile banking, digital checkouts, and transactional flows with automated consent logging and real-time policy binding. Explore FT Embedded Insure.
Insurance distribution does not end once the premium is paid. When policy records are scattered across different siloed software systems, customer service teams struggle with delays and manual record-checking.
A centralized bancassurance engine streamlines:
- Centralized Policy Repository: Unified access to all active policies across carriers from a single screen.
- Automated Renewal Tracking: Proactive SMS, WhatsApp, and email alerts driving higher retention and renewal persistency.
- Self-Service Customer Portals: Borrowers can view policy schedules, download certificates of insurance (COIs), and submit service requests 24/7.
- Cancellation & Foreclosure Refunds: Pro-rata refund calculations triggered automatically upon early loan payoff.
Claims servicing is the ultimate moment of truth in insurance. When policyholders experience an insured event, they invariably turn to their bank or lender for guidance. Disjointed, paper-heavy claims processes result in delayed document collections, poor status visibility, and customer frustration.
Digital claims management software equips frontline branch staff and customer care teams with:
- Digital First Notice of Loss (FNOL): Guided mobile and web intake forms to register claims instantly.
- AI-Assisted Document Verification: Automated OCR validation of discharge summaries, KYC records, and death/hospital certificates.
- Real-Time Insurer Tracking: Live status synchronization with insurer claim adjudication portals.
FondosTech FT Digital Claims: Unifies 50+ insurer claims APIs, offering 98.5% OCR verification accuracy and tracking cashless approvals to accelerate SLA turnaround times. Explore FT Digital Claims.
As distribution volumes scale across thousands of monthly policies and multiple insurer tie-ups, finance departments face enormous manual workloads reconciling:
- Internal loan booking records vs insurer sales statements
- Gross premium collected vs net premium remitted
- Corporate agency fee schedules, TDS deductions, and clawbacks
Manual spreadsheet comparisons lead to uncollected fee revenue, delayed payout disclosures, and audit findings. Automated reconciliation software ingests raw insurer statements, matches records on unique identifiers, and highlights discrepancies instantly.
FondosTech FT Reconciliation: Replaces fragile Excel files with automated statement parsing, commission matching, and mismatch alerting—giving CFOs and finance leaders complete revenue visibility. Explore FT Reconciliation.
Insurance distribution is a rigorously regulated activity in India. Digital enablement must never compromise statutory obligations set forth by the Reserve Bank of India (RBI) and the Insurance Regulatory and Development Authority of India (IRDAI).
Key mandatory operational controls include:
- Product Suitability & Disclosure: Clear, upfront disclosures of terms, premiums, and policy features.
- Voluntary Selection (No Coercive Bundling): Under RBI corporate agency guidelines, loan disbursal cannot be tied compulsively to insurance purchase; customer opt-in must be genuinely voluntary and verifiable.
- Audit Trails at Transaction Level: Time-stamped consent records, IP logs, and borrower authorization records.
- Grievance Redressal Mechanisms: Documented audit trails of consumer inquiries, complaints, and resolution SLAs.
FondosTech FT Compliance Shield: Built-in regulatory checks, immutable audit trails, and automated IRDAI compliance reporting ensure financial institutions stay 100% inspection-ready. Learn more about FT Compliance.
How FondosTech Supports Insurance Distribution for Banks & NBFCs
FondosTech provides an end-to-end suite of modular insurtech products designed specifically to accommodate diverse banking and lending distribution models:
| FondosTech Solution | Primary Capability | Institutional Benefit |
|---|---|---|
| FT Lending Insure | Loan-linked insurance & full lifecycle management | Connects insurance with loan disbursal, servicing, and foreclosure refunds. |
| FT Embedded Insure | In-journey, contextual checkout insurance integration | Presents bite-sized policies inside existing mobile apps and payment flows. |
| FT D2C Insure | Direct-to-consumer digital quotation and comparison journeys | Enables bank customers to purchase retail insurance independently online. |
| FT Digital Claims | Digital FNOL intake, AI document checks, and status tracking | Accelerates claims resolution and provides branch teams with live status tracking. |
| FT Reconciliation | Automated statement matching and commission reconciliation | Eliminates revenue leakage and replaces manual spreadsheet work. |
| FT Compliance | Audit trails, mandatory workflow checks, and IRDAI reporting | Guarantees institutional governance and full compliance readiness. |
What Banks & NBFCs Should Look for in Bancassurance Software
Selecting an enterprise bancassurance partner requires rigorous evaluation across technological, architectural, and operational criteria:
| Evaluation Criterion | What Must Be Assessed |
|---|---|
| Insurer Connectivity | Pre-built integrations with major life, general, and health insurers relevant to corporate agency agreements. |
| System Compatibility | Turnkey API and webhook compatibility with Core Banking Systems (CBS), Loan Origination Systems (LOS), and CRMs. |
| Product Flexibility | Configurable support for life, health, motor, personal accident, and credit-linked group insurance products. |
| Customer Experience | Frictionless opt-in screens, transparent disclosures, OTP/e-sign consent, and zero customer redirects. |
| Claims & Servicing | Centralized visibility for tracking endorsements, customer service tickets, and claim settlements post-sale. |
| Compliance Controls | Strict access management, tamper-proof audit trails, and automated regulatory filing reports. |
| Finance Operations | Automated multi-carrier statement reconciliation, commission mismatch alerts, and payout tracking. |
| Enterprise Scalability | High-throughput cloud architecture capable of handling millions of transactions with 99.9% uptime. |
Strategic Conclusion: Transforming Distribution into an Engine of Growth
For banks and NBFCs, expanding insurance distribution is no longer just about adding new insurer agreements. True scale demands modern technology capable of orchestrating surging policy volumes, maintaining carrier relationships, servicing borrowers, and fulfilling regulatory mandates.
By adopting an integrated bancassurance platform, financial institutions can embed protection directly into existing banking and lending journeys. This transforms insurance from a manual administrative chore into a high-margin, customer-centric revenue driver.
Frequently Asked Questions (FAQs)
Bancassurance software is technology that enables banks and authorised financial distributors to manage insurance quotations, sales, policy issuance, servicing, insurer integrations and reporting through connected workflows.
Bancassurance software helps NBFCs integrate eligible insurance products with lending journeys, maintain loan-linked policy records, automate selected operational tasks and track policy servicing and cancellations.
Yes. Eligible NBFCs are permitted to undertake insurance products, subject to applicable requirements as prescribed by the Reserve Bank of India and the Insurance Regulatory and Development Authority of India (IRDAI) and the appropriate distribution registration or arrangement. They must work within the limits of the permissions and restrictions of the relevant regulatory framework.
Insurance should not be automatically presented as compulsory because a customer is borrowing. The RBI’s corporate agency provisions are voluntary and do not allow coercive tying of insurance to financial services. Specific loan and asset-protection conditions must also be assessed under the applicable rules.
Bancassurance refers to insurance distributed through banks. Embedded insurance is a technology-enabled distribution model in which an insurance offer appears within another product or transaction journey. A bank or NBFC can use embedded insurance technology as part of its authorised distribution activities.
Yes. The API-enabled bancassurance software can connect to multiple supported insurers.
FondosTech provides insurance technology solutions covering lending insurance, embedded insurance, digital policy journeys, claims management, reconciliation and compliance-related workflows. These solutions can be configured around supported products, insurer integrations and institutional operating requirements.